
There is a pay cut hidden in your pension papers.
It does not hit the day you retire.
It hits the day you die. And your spouse may not know about it yet.
If you have a pension through a private company or a union, and you were offered a pension lump sum instead of the monthly check, this article is for you.
One quick note before we start. This is for learning only. Please do not buy or sell any insurance or investment product without talking to a licensed advisor first.
The one question nobody asks
When people sit at the kitchen table and look at their pension papers, they ask three things.
-
- How big is the check each month?
-
- How big is the buyout amount?
-
- Do I get a cost of living raise?
Those are fair questions.
But none of them is the biggest one.
The biggest question is this: “What happens to my spouse’s income the month after I’m gone?”
Not the month you retire. The month after you die.
Almost nobody asks it. And that is a problem.
Why this happens
A pension is a promise from a company. Every single benefit the company adds for your spouse has to come out of your check.
That isn’t unfair. That is just how the math works.
A pension lump sum is just a price tag on that same promise.
So here is the rule to write down:
The version of the pension that pays you the most is the version that pays your spouse the least.
Sometimes it pays your spouse nothing at all.
And it is not a secret. It is in the papers. It is just a few pages deep, written in a way that nobody reads out loud.
A real case
I met with a couple not long ago.
The husband is 64. The wife is 59.
He has a pension from a very big company. You would know the name. His pension has no cost-of-living raise, so that check never grows.
She has a government pension with a raise built in. So at least one of them has some protection from rising prices.
He also planned to work two more years.
He had three choices.
| Choice | What he gets | What she gets |
|---|---|---|
| One | $350,000 buyout | Possible Death Benefit if the money last |
| Two | $2,000 a month, about $24,000 a year, for his life only | Nothing. No check, no death benefit, no money |
| Three | $1,900 a month, about $23,000 a year | Half. About $950 a month |
Choice one was the pension lump sum of $350,000.
Choice two paid him the most each month. It also left his wife with nothing.
He was leaning toward choice three. He should. It costs him about $100 a month. That is not a change in lifestyle.
But look at where his wife ends up.

The part that needs a closer look
If he passes away, her check from his pension goes from $1,900 a month down to $950 a month.
She takes a 50% pay cut at the exact moment she loses her husband.
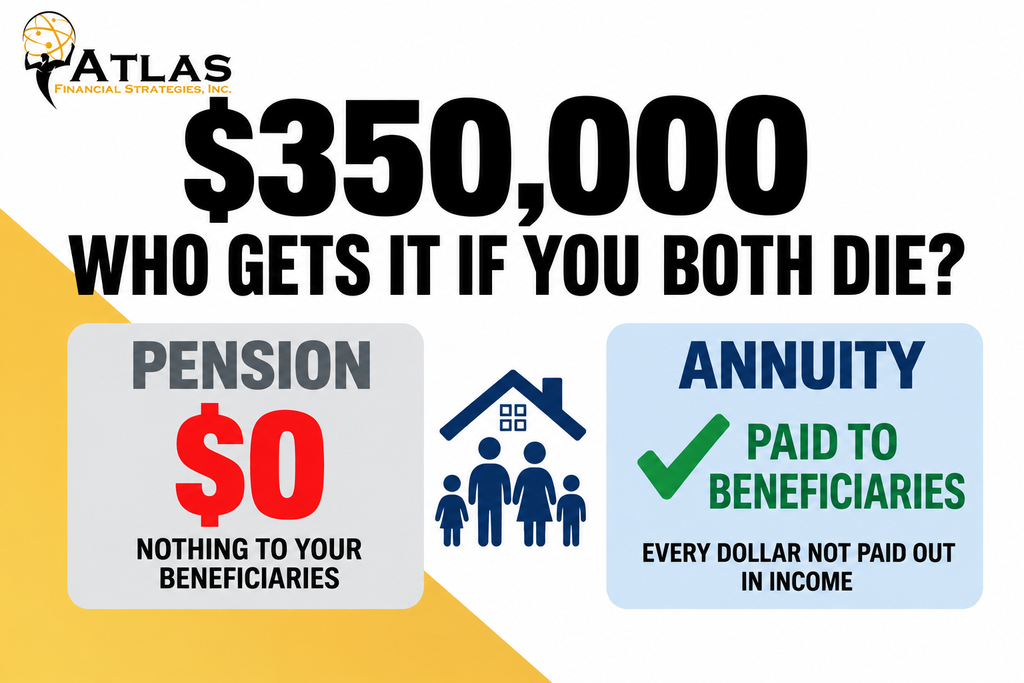
And if they both pass away, there is no death benefit at all. Not to the kids. Not to a charity. Not to a trust.
The pension keeps whatever it did not pay out. That is just how pensions work.
That is the pay cut. It is real, and it is sitting in the papers right now.
We ran the same money both ways
We did a fair comparison. Same money. Same question.
We looked at a fixed indexed annuity with an income rider from an A-rated company. We held the income back for two years.
We ran that same pension lump sum through it.
Here is what came out.
| Pension, choice three | Annuity | |
|---|---|---|
| Each month | $1,900 | $2,240 |
| Each year | About $23,000 | About $27,000 |
| If he passes | Drops to $950 | Does not drop |
| Death Benefit if they both pass | $0 | Every dollar not paid out goes to the people they named |
Right away, he gets $240 more each month than the pension.
And $340 more each month than the survivor choice he was leaning toward.
But the extra few hundred dollars is not the main point.
The main point is this. When he passes, her check does not drop. Not by one dollar.
It is a joint lifetime check with a guarantee from the insurance company. That is what it is built to do.
“Marty, this is fear talk”
You may be thinking that. I do not want to sell on fear.
So let’s take every pension failure off the table.
Forget the news stories about plans that failed. Forget the plans handed over to the Pension Benefit Guarantee Corporation. Forget that the backstop itself needed taxpayer money to help stay solvent.
Set all of it aside.
Even if every pension in this country paid every dollar it promised, the annuity still wins in this case.
-
- It wins on the monthly check.
-
- It wins on the check your spouse keeps.
-
- It wins on the death benefit.
That is not fear. That is math.
Let me be fair to pensions
Some pensions are very good.
If you have a federal pension, or a state plan with a real cost-of-living raise built in, and the plan is well funded, you probably do not need me.
That is a real asset. I would not touch it. I would never tell you to touch it.
This is for the person with a private company plan. Or a plan with no raise built in. Or a survivor choice to make. Or an offer sitting on the table with a deadline on it.
“But I get control”
Yes. If you take the pension lump sum, you get control of the money.
That is a real benefit. I will not pretend it is not.
But control only matters if the money still does the job you need it to do.
Say you take that $350,000 and put it in a managed account. Now you own:
-
- The market risk.
-
- The sequence of returns risk.
-
- The job of making it last 30 years, or longer, for two people.
Most advisors will tell you to start taking about 4%. That is $14,000 a year for this particular client.
That is almost $13,000 less than the guaranteed check in the same case.
Maybe the $350,000 lasts. Maybe it does not. That is the risk you take on.
If you buy the income instead, you hand those three problems to an insurance company. And you keep the paycheck.
Neither path is free. They are just two different goals.
The other side, honestly
I want to be straight with you.
If you take the pension lump sum and invest it, you may get to watch the balance grow.
You also get to watch it fall. In the annuity, you never see the balance drop because of a bad market.
For some people, that means freedom. For others, it keeps them awake at night.
You have to know which one you are before you sign. I would rather ask you that now than have you resent this choice for 30 years.
The same is true if you keep the pension and turn the check on.
The real choice
It is not pension versus annuity.
It is two questions.
-
- Which plan pays you the most for as long as you live?
- Which plan keeps paying the person you love after you’re gone?
Answer those two, and the papers get much less confusing.
The pension company is not your enemy. The annuity company is not your friend. They both just use math.
Your job is to pick the math that helps your family the most.
What to do next
Do not rush this.
Get both numbers. The pension lump sum and the income annuity. Put them side by side.
Then ask the two questions again. Which pays you more over your life? Which protects your spouse?
It does not have to be a fight. It is just two sets of numbers. Then you pick the one that takes care of your family.
If you want your numbers run side by side, go to atlasannuity.com and book your Income Clarity Call. It is free. There is no pressure and no hype. We just run the math.
Podcast Episode 123: Pension Lump Sum vs Annuity: The Survivor Benefit Nobody Checks
Download Episode 123: Pension Lump Sum vs Annuity: The Survivor Benefit Nobody on Apple Podcast