
People ask me this question all the time.
“Marty, I want to retire in five years. Should I put my money in a fixed indexed annuity with an income rider? Or should I use a MYGA and then buy income later?”
It’s a good question. Both plans try to do the same thing. They both turn a lump of money into a paycheck you can’t outlive.
But just because two plans aim at the same goal does not mean they land in the same place.
Sometimes the gap is small. Sometimes it’s a quarter of a million dollars.
Let me show you the math.
First, What Are These Two Things?
A fixed indexed annuity with an income rider. You give money to an insurance company. It gives you a promise. That promise says your future income will grow by a set amount each year you wait to start the income. If you wait five years, you know today what your income will be in five years.
A MYGA. This stands for Multi-Year Guaranteed Annuity. It’s simple. Think of it like a bank CD sold by an insurance company. You put money in. It earns a set interest rate for a set number of years. No surprises.
Then, when the MYGA term ends, you take the money and buy a SPIA. A SPIA is a Single Premium Immediate Annuity. You hand over a lump sum, and it pays you income for life.
So the MYGA plan is two steps. Grow the money first. Buy the income second.
That sounds fine. But there’s one big problem hiding in it.
The Numbers
Here’s the example I ran. A married couple, both 63. They plan to retire at 68. They have $100,000 set aside just for income.
| Plan | What Happens | Yearly Income at 68 |
|---|---|---|
| Fixed indexed annuity with income rider | Income locked in today | $12,000 |
| 6% MYGA, then a SPIA at 68 | $100,000 grows to about $134,000 | $10,287 |
Same money. Same five-year wait. One plan pays $1,713 more every single year, for life.
Now let’s use bigger numbers.
Say this couple sets aside $500,000 instead.
| Plan | Yearly Income |
|---|---|
| Fixed indexed annuity with income rider | $60,000 |
| 6% MYGA, then a SPIA at 68 | $51,500 |
That’s $8,500 less every year.
Add it up over time:
-
- Over 20 years: $171,000 lost
-
- Over 25 years: $214,000 lost
-
- Over 30 years: over $250,000 lost
And nothing changed. Same money. Same goal. Same wait.
Only the plan changed.
That’s why I tell people to look at the big number, not the small one.

The Real Difference: Worth vs. Income
Here’s the part most people miss.
When you buy a MYGA, you lock in your interest rate. That part is a promise. The insurance company can’t change it.
But you do not lock in what a SPIA will pay five years from now.
That payout depends on:
-
- Interest rates at that time
-
- What the insurance companies are pricing
-
- Life expectancy tables
-
- Which income option you pick then
You don’t control any of those things.
So the $134,000 sitting there in year five feels very safe. It’s a real number. But that number does not tell you how much income it will buy in five years.
A fixed indexed annuity with an income rider works the other way. You give up knowing your exact balance, except for the Minimum Guaranteed Surrender Value. In return, you know today what your income will be the day you stop working.
So ask yourself this question.
If you know you will need a certain amount of income in five years, do you want to leave that up to what insurance companies may be offering in the future?
Or do you want it settled now?
The Risk of Waiting
Let’s be fair to the MYGA plan. The numbers I used come from rates today, in November 2026. Rates are high right now.
That SPIA quote is not a promise for five years from now.
If rates go up, the MYGA then SPIA plan could look better. If rates go down, it could look worse.
We just don’t know.
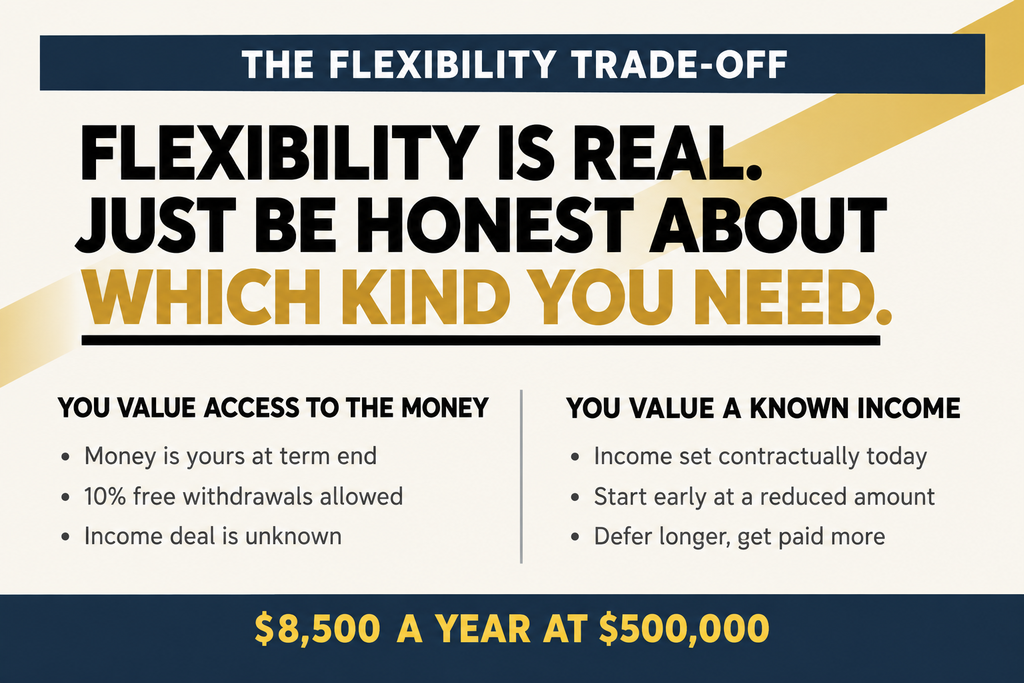
That is the trade. The MYGA gives you a known balance. The income rider gives you a known income.
For many people heading into retirement, the income is the number that matters.
What About Getting to Your Money?
I’m not saying the fixed indexed annuity always wins. It doesn’t.
The MYGA is more flexible in one clear way. When the term ends, the money is yours. You can move it, spend it, or use it for something else.
Most MYGAs also let you take some money out along the way. Often that means free interest withdrawals, or up to 10% of the account value.
But there’s a catch. If you need income early, you have to start it with the company already holding your money. You don’t get to shop around for the best deal.
The income rider has its own give and take.
-
- Need income at year three instead of five? You can start it early, but you get less.
-
- Get to year five and don’t need it yet? Keep waiting. The income grows bigger.
That choice has real value.
Start With the Job, Not the Product
This is the most important idea in this whole article.
Every dollar you save for retirement should have a job.
Some money is for growth. Some is for emergencies. Some is for travel or a new vehicle or helping the grandkids.
Some money is for income. Income you can’t outlive.
Those are all different jobs. And different jobs need different tools.
So here’s how I work.
Say you have $5,000 a month coming in from Social Security and a pension. You need $8,000 a month to live the way you want.
You have a $3,000 gap.
Now we have a real problem to solve. Now we can compare plans.
Maybe the income rider gives you the most income. Maybe a SPIA makes more sense because you’re retiring right now. Maybe a MYGA fits because you’re not sure when you’ll need the money.
Notice what we did not do. We did not start with a product.
We started with the problem.
So Which One Is Best?
There is no such thing as the “best” annuity.
There is only the best annuity for the job your money needs to do.
If you know that money is for guaranteed lifetime income, then in this example the fixed indexed annuity with the income rider is the stronger choice. It pays more, and you know the number today.
If you might need that money for something else, or you’re not sure you’ll want income in five years, then the MYGA is the more sensible tool.
One more thing. Always check the whole market before you buy any annuity. Rates and offers change. A 6% interest rate sounds great. And it is great if your goal is to grow money.
But if your goal is income, the question changes. The question becomes: “How much income will this money actually pay me?”
The Number to Remember
Most people look at one number. How much will I have when I retire?
That’s the wrong number.
The number that matters is this: how much guaranteed income will that money pay me when I retire?
Those are two very different questions. And only one of them tells you how your retirement will actually feel.
If you’re within five years of retirement and you’re trying to pick between these two paths, let’s use your real numbers. Not a guess. Not a sample.
Book a retirement income clarity call. Bring the amount you’ve set aside and the age you want income to start. I’ll run both plans and show you the gap in real dollars.
Because the gap might be small. Or it might be a quarter of a million dollars.
You should know which one before you sign.
Podcast Episode 122: MYGA vs Fixed Indexed Annuity: Which Produces More Guaranteed Income?
Download Episode 122: MYGA vs Fixed Indexed Annuity: Which Produces More Guaranteed Income? on Apple Podcast